
Payment processor decline is the formal term for what happens when a transaction is rejected before funds reach the merchant. Understanding why payment processors decline ecommerce merchants is the first step to recovering lost revenue and protecting your approval rates. 35% of declined transactions lead to immediate cart abandonment or a customer switching to a competitor. That number represents real money leaving your business every day. Declines fall into three categories: issuer decisions, merchant risk signals, and technical or operational failures. Each category requires a different fix, and confusing them leads to wasted effort.
Why do payment processors decline ecommerce merchants?
Payment processors decline ecommerce merchants when a transaction or merchant profile presents unacceptable risk. The decline itself is not always the processor’s decision. Three separate parties can trigger a rejection: the card-issuing bank, the processor’s own risk engine, or a technical failure in the payment flow.
Issuer-based declines are the most common. They occur when the bank that issued the customer’s card refuses to authorize the charge. Processor-level declines happen when the merchant’s own account triggers a risk flag. Technical declines occur when data errors or system failures prevent the transaction from completing at all.
Knowing which category caused a decline tells you exactly where to act. A merchant who keeps retrying a hard decline wastes resources and risks flagging the customer’s account. A merchant who ignores a soft decline loses a sale that was recoverable with a simple retry or updated card credential.
What issuer-related factors cause payment declines in ecommerce?
The card-issuing bank controls the final authorization decision on every transaction. Common issuer decline reasons include:
- Insufficient funds. The customer’s account balance or credit limit cannot cover the charge.
- Expired card. The card number is valid but the expiration date has passed.
- Suspected fraud. The issuer’s risk model flagged the transaction as unusual based on location, amount, or spending pattern.
- Account restrictions. The card is frozen, closed, or limited by the bank.
- Authentication failure. The customer did not complete a 3D Secure challenge, or the authentication timed out.
Issuers use behavior-based fraud models that score every transaction in milliseconds. A customer who normally shops locally and suddenly places a large order from an unfamiliar merchant will often trigger a fraud flag, even if the card is valid and the customer is legitimate. This is a false decline, and it frustrates customers who have done nothing wrong.
Hard declines vs. soft declines
Distinguishing soft declines from hard declines is the most practical skill a merchant can develop. A soft decline is temporary. Insufficient funds, a temporary hold, or a failed 3D Secure challenge can all be resolved. A hard decline is permanent. Stolen cards, closed accounts, and fraud blocks require a different response entirely. Retrying a hard decline will not succeed and may trigger additional fraud flags on the customer’s account.
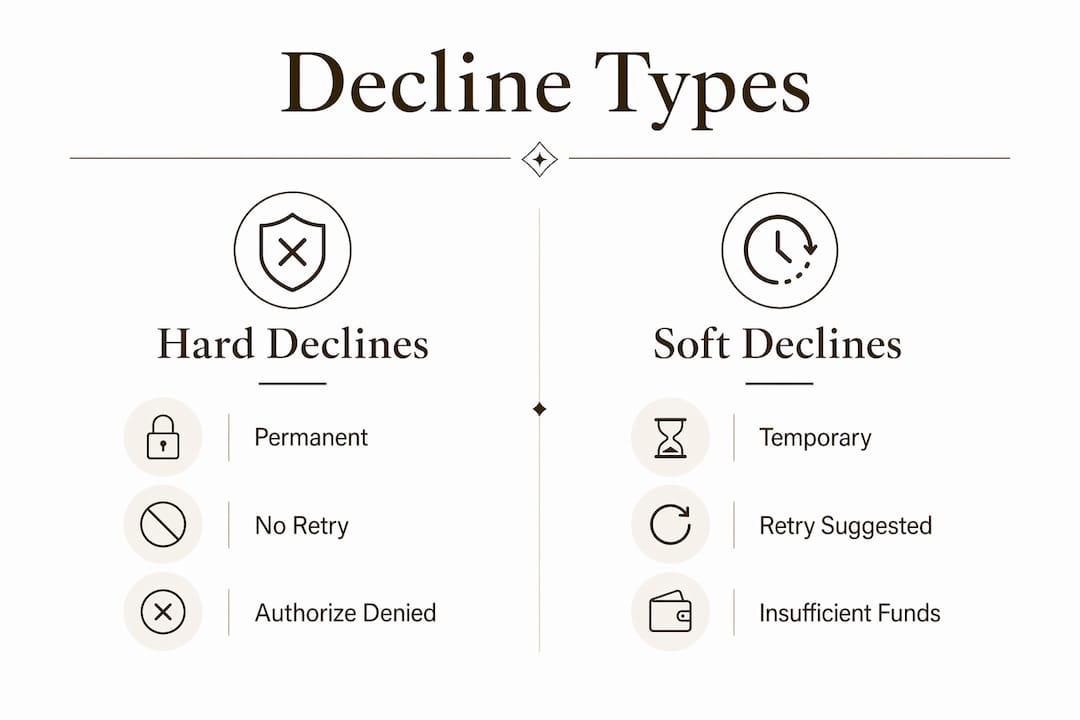
Decline codes in your gateway dashboard identify the type. Codes like “do not honor” or “insufficient funds” signal soft declines. Codes like “pick up card” or “lost/stolen” signal hard declines. Reviewing these codes weekly gives you a clear picture of where your approval rate is bleeding.
Pro Tip: Wait at least 24 hours before retrying a soft decline. Retrying too quickly signals desperation to the issuer’s fraud model and reduces your chance of approval on the second attempt.
How merchant risk profile influences payment declines and account restrictions
Processors do not just evaluate individual transactions. They evaluate you as a merchant continuously. Automated machine learning models score hundreds of risk variables across your entire account, including chargeback rates, refund patterns, transaction velocity, and volume spikes. This evaluation runs in the background at all times, and most merchants never see it until something goes wrong.
The key risk metrics that trigger account reviews or holds are:
- Chargeback rate. Rates above 0.9% trigger formal reviews. Visa and Mastercard each maintain their own monitoring programs with separate thresholds. Processors begin scrutinizing accounts well before those network limits are reached.
- Refund rate. Refund rates above 5% signal product or fulfillment problems that often precede chargebacks. Rates above 10% are treated as red flags and correlate directly with account restrictions.
- Transaction velocity. A sudden spike in transaction volume, especially from new customers or unfamiliar geographies, triggers automated holds.
- Volume anomalies. Processing $50,000 in a month when your approved volume is $10,000 will freeze your account, even if every transaction is legitimate.
Payment processors use continuous, automated risk evaluation that flags accounts based on thresholds for chargebacks, refunds, transaction anomalies, and volume spikes, often with little transparency to merchants. Most merchants discover restrictions only after account holds or freezes occur, not before.
New merchants face more scrutiny than established ones. A processor has no processing history to evaluate, so it applies conservative limits and watches closely. Frequent processor switching makes this worse. Each new processor starts your risk evaluation from zero, and a pattern of switching signals instability to underwriting teams. Building a continuous, verified processing history is the strongest signal of merchant trustworthiness you can send.
Understanding payment compliance requirements also matters here. Processors factor regulatory compliance into their risk models, and gaps in compliance documentation accelerate account reviews.
Pro Tip: Pull your chargeback and refund rates from your processor dashboard every two weeks. Do not wait for a notice. Catching a trend at 0.6% gives you time to act before you hit the 0.9% review threshold.
What technical and operational issues cause ecommerce payment declines?
Technical declines happen before the issuer ever sees the transaction. Data quality errors and authentication failures generate false declines that frustrate customers and inflate your decline rate without any actual fraud or risk problem.
| Technical issue | What causes it | Recommended fix |
|---|---|---|
| Incorrect card number | Customer data entry error or outdated stored credential | Enable real-time card validation at checkout |
| Billing address mismatch | Customer moved or entered an abbreviation | Use address verification with flexible matching rules |
| Expired stored card | Subscription merchant using old token | Implement account updater services |
| Gateway routing failure | Misconfigured routing rules or network timeout | Add a secondary gateway as a failover |
| Overly aggressive fraud filter | Rules set too broadly, blocking legitimate orders | Segment rules by customer type and order history |
| Unsupported card type | Processor does not accept certain card networks | Confirm card acceptance scope with your processor |
Upstream failures at the processor or network level also cause declines before authorization reaches the issuer. Routing problems, missing transaction data fields, and network rule violations all produce declines that look like issuer rejections in your dashboard but originate earlier in the payment flow. Identifying where in the flow a decline occurs is the only way to target the right fix.
Fraud filters deserve special attention. A filter tuned too tightly blocks legitimate customers, especially first-time buyers or customers in new geographies. The result is a false decline rate that costs you revenue without improving security. Reviewing AI-driven payment monitoring practices helps merchants understand how modern fraud tools should be calibrated.
Pro Tip: Run test transactions from different devices, browsers, and geographic locations monthly. Decline spikes in a specific region or device type point directly to a misconfigured rule or routing issue.
What practical steps can ecommerce merchants take to reduce payment declines?
Reducing payment declines requires action across all three categories: issuer factors, merchant risk, and technical issues. The merchants who improve approval rates fastest are the ones who treat decline data as a reporting system, not just a failure notification.
Start with these practices:
- Segment your decline codes. Separate issuer declines from processor declines from technical declines. Each group needs a different response.
- Cleanse customer data at checkout. Use real-time card validation, address verification, and auto-formatting to eliminate data entry errors before they reach the gateway.
- Tune fraud rules by customer segment. Apply stricter rules to first-time buyers and looser rules to returning customers with clean order histories. Blanket rules create false declines.
- Communicate with your processor before volume spikes. If you are running a promotion or expect a seasonal surge, notify your processor in advance. Unannounced spikes trigger automated holds.
- Use account updater services for subscriptions. These services automatically refresh expired or replaced card credentials, eliminating a major source of recurring billing declines.
- Implement tokenization and digital wallets. Tokenized card data reduces data entry errors and improves authentication success rates, especially on mobile.
- Retry soft declines with a structured schedule. Wait 24 hours, then retry once. If the second attempt fails, prompt the customer to update their payment method.
- Monitor your chargeback and refund rates weekly. Set internal alerts at 0.5% chargeback rate and 4% refund rate so you act before processors do.
The merchants who manage payment processing proactively consistently outperform those who react only after account holds or terminations occur.
Key Takeaways
Payment processors decline ecommerce merchants due to issuer decisions, merchant risk signals, and technical failures, and each category requires a distinct response to recover approval rates.
| Point | Details |
|---|---|
| Issuer declines are the most common | Insufficient funds, expired cards, and fraud flags from the issuing bank cause the majority of rejections. |
| Hard vs. soft declines require different actions | Soft declines are recoverable with retries; hard declines require a new payment method or customer outreach. |
| Chargeback rates above 0.9% trigger reviews | Processors monitor trends continuously and act before Visa or Mastercard network thresholds are reached. |
| Technical failures cause false declines | Data errors, gateway misconfigurations, and overly aggressive fraud filters block legitimate transactions. |
| Processor switching resets your risk history | Building a continuous processing record is the strongest signal of merchant trustworthiness. |
What I’ve learned about declines that most merchants find out too late
The most damaging thing about payment processor declines is not the individual lost sale. It is the information gap. Processors do not send you a report explaining why your approval rate dropped or what risk score your account carries. You find out when a hold lands or an account gets terminated. By then, the trend has been building for weeks.
I have seen merchants spend months chasing issuer decline codes when the real problem was a chargeback rate creeping toward 0.8%. The processor’s automated model had already flagged the account. The merchant had no idea. That information asymmetry is the core challenge, and it is not going away.
The merchants who handle this best do two things consistently. They pull their own risk metrics before the processor does, and they communicate with their processor proactively. A quick call before a major promotion, a monthly review of refund trends, a weekly check of decline code distributions. These habits are not complicated. They are just rare.
Frequent processor switching is the other mistake I see regularly. Every switch resets your processing history to zero. Underwriting teams at the new processor see a merchant with no track record and apply maximum scrutiny. The instability signal alone can trigger tighter limits. Staying with one processor and building a clean history over time is a better strategy than chasing marginally better rates.
Choose a processor that gives you visibility into your risk standing and communicates with you before problems escalate. That transparency is worth more than any fee difference.
— Peter
Davincipay helps high-risk merchants get approved and stay approved
Ecommerce merchants in complex verticals face payment declines at a higher rate than standard retail. Supplements, nutraceuticals, telehealth, and subscription businesses all carry risk profiles that standard processors are not built to handle.

Davincipay specializes in high-risk payment processing for exactly these merchants. We work with domestic and international acquiring relationships, provide transparent risk evaluation, and support merchants through volume spikes without unexpected holds. Our underwriting team reviews your account before problems surface, not after. Merchants in the supplement and nutraceutical space trust Davincipay because we understand their risk environment and build processing solutions around it. Apply now and get a fast approval decision from a team that knows your industry.
FAQ
What is the most common reason for payment declines in ecommerce?
Issuer-based reasons, including insufficient funds, expired cards, and suspected fraud, are the primary cause of payment declines at checkout. These decisions come from the card-issuing bank, not the merchant’s processor.
What is the difference between a hard and soft decline?
A soft decline is temporary and may be resolved through a retry or updated card credential. A hard decline is permanent and requires the customer to provide a different payment method.
What chargeback rate triggers a merchant account review?
Chargeback rates above 0.9% trigger formal account reviews by processors, and scrutiny often begins well before that threshold is reached.
Does switching payment processors hurt my approval rates?
Yes. Frequent processor switching signals instability to underwriting teams and resets your processing history, which can result in tighter limits and deeper investigations at each new processor.
How can I tell if a decline is technical or issuer-related?
Review the decline code in your gateway dashboard. Codes referencing routing failures, missing data, or authentication timeouts indicate technical issues. Codes referencing account status, fraud, or funds indicate issuer decisions.



