
Finding a high-risk payment processor that delivers fast approvals, ongoing support, and minimized risk of account freezes is unreliable for merchants. Mainstream processors restrict regulated or high-risk sectors, gate pricing, or lack specialized underwriting and chargeback support. This comparison lists features, onboarding times, and service strengths so merchants can pick a payment processor that actually protects their cash flow.
Table of Contents
- DavinciPay
- Adaptiv Payments
- StokePay
- QuadraPay
- L3 Payments
- Durango Merchant Services
- Comparison of alternatives
DavinciPay
At a Glance
DavinciPay reports a fast approval process within 24 hours. That claim is the clearest signal the vendor pitches to merchants who need rapid onboarding. The company targets stores and services that traditional processors often refuse. The product emphasizes ongoing account support to reduce freeze and interruption risk.
Core Features
The vendor advertises PCI Level 1 certification alongside built-in compliance features such as age verification. A real-time dashboard tracks payments, disputes, and payouts so you can react to chargebacks quickly. Flexible checkout options include online checkout, pay-by-link, and subscription handling plus underwriting and fraud prevention tools.
Key Differentiator
DavinciPay focuses on fast onboarding and ongoing support for industries banks often decline. That specialization covers nutraceuticals, telehealth, CBD, vaping, adult content, gaming, and subscription models. The provider pairs acquiring relationships with chargeback mitigation and underwriting assistance to keep accounts active. This operational support aims to reduce the common friction high-risk merchants face.
Pros
Speedy onboarding is practical for merchants who need uninterrupted revenue while switching processors. Specialized support helps merchants rejected elsewhere get underwritten, onboarded, and monitored. Security stands out because the vendor advertises PCI Level 1 certification and real-time monitoring. Transparent pricing and account monitoring appear as selling points. Chargeback management tools and dispute fightback support reduce manual workload for teams handling disputes.
Cons
- Limited public detail on fees and exact pricing tiers, which suggests costs may run higher for high-risk verticals.
Notable Integrations
DavinciPay integrates with Shopify and WooCommerce. Those two platforms cover most ecommerce storefronts and subscription plugins. Integration support helps you connect checkout flows and track settlements in the dashboard.
Who It’s For
This service fits high-risk merchants that need fast, compliant payment access. You run a CBD, nutraceutical, telehealth, vaping, gambling, adult, or membership business and face declines or freezes from mainstream processors. You also need chargeback support and ongoing underwriting assistance to keep accounts live.
Unique Value Proposition
The real-time dashboard for payments, disputes, and payouts gives your team one place to monitor risk and cash flow. That operational visibility reduces reaction time on disputes and lets support intervene before an account is placed on hold. For businesses that require quick fixes and active monitoring, this changes daily operations and reduces downtime.
Real World Use Case
A CBD retailer losing access to its processor can move to DavinciPay, onboard quickly, and resume sales within days. The merchant uses the dashboard to spot a spike in disputes and launch the dispute fightback workflow. Customer service and underwriting support then manage documentation to prevent account freezes and keep payouts flowing.
Pricing
Pricing is not publicly listed and the product entry is informational only. Expect merchant-specific quotes based on industry risk, volume, and transaction mix. Contact the vendor for a custom rate and contract details.
Website: https://davincipay.ai
Adaptiv Payments
At a Glance
Over 20 years of experience backs Adaptiv Payments’ work with merchants in CBD, travel, online gaming, and similar sectors. The vendor advertises high approval rates through an extensive banking network and highlights fast onboarding and transparent pricing. Their offering covers merchant accounts, a payment gateway, a virtual terminal, and ecommerce connectors.
Core Features
Adaptiv Payments combines merchant account underwriting with a payment gateway and a virtual terminal to support online sales and phone orders. The platform includes real-time fraud monitoring and risk management tools and supports global processing in multiple currencies. It also integrates with major ecommerce platforms and provides chargeback prevention and dispute resolution tools without hidden fees.
Key Differentiator
Adaptiv Payments pairs niche high risk underwriting experience with a customizable payment ecosystem and broad acquiring relationships. That mix lets the vendor route accounts to banks that understand regulated sectors and unusual risk profiles. This capability targets merchants whose product categories routinely trigger declines with mainstream processors.
Pros
Adaptiv Payments delivers fast approvals and a quick onboarding flow that helps merchants start processing sooner. The company emphasizes helpful customer support and industry expertise, which merchants often need when rules and compliance vary by region. Its fraud and chargeback prevention features reduce dispute work for merchants and support higher processing uptime.
Cons
-
Pricing is not published publicly. The product data labels pricing as not applicable and informational only, so you must request specifics.
-
No notable integrations are listed in the product data, which may require custom work for niche platforms.
-
Public third party reviews do not surface consistent negative points, which makes independent benchmarking of weaknesses difficult.
When It May Not Fit
If you run a low risk online store that qualifies for standard processors, Adaptiv Payments may not be the right match. Businesses that want widely published flat fees and off the shelf low risk pricing might find this service misaligned with their needs. Shops needing many prebuilt integrations should verify support before committing.
Who It’s For
This service fits business owners in high risk verticals such as CBD, nutraceuticals, travel, gaming, and adult entertainment who need compliant merchant accounts and quick approvals. You should have transaction profiles or products that mainstream processors decline or restrict. Owners who value vendor underwriting and tailored account placement will benefit most.
Real World Use Case
A CBD retailer unable to secure processing obtained a tailored merchant account through Adaptiv Payments. The retailer reported quick setup, routed acquiring that accepted the vertical, and integrated fraud controls that lowered disputes. That setup let the merchant process online sales reliably while navigating evolving regulation.
Pricing
Pricing is not publicly listed. The product data states: Not applicable — informational only. Prospective buyers will need to contact the vendor for account level pricing and terms.
Website: https://adaptivpayments.com
StokePay
At a Glance
Cashless ATM solutions for cannabis dispensaries are a core offering. StokePay targets merchants in hemp, CBD, and adult use cannabis and focuses on reducing cash handling at point of sale. The company couples payment acceptance options with consultative onboarding and documentation support for regulated merchants.
Core Features
StokePay combines high risk payment processing expertise with compliance assistance and merchant account setup. It offers cashless ATM deployments for dispensaries, plus pre underwriting and documentation support to help merchants present underwriters with required paperwork. The vendor also provides industry specific consultation for ISOs and agents.
Key Differentiator
The one thing that sets StokePay apart is its narrow focus on high risk and emerging industries. That focus manifests as tailored compliance work and merchant account structures built specifically for hemp, CBD, and cannabis sellers.
Pros
StokePay brings specialized knowledge for merchants who face underwriting friction and high chargeback scrutiny. The service emphasizes personalized consultation and hands on onboarding, which helps newer dispensaries get merchant accounts and payment setups more quickly. Its cashless ATM option addresses a common operational pain for dispensaries while reducing onsite cash exposure.
Cons
- Limited public user feedback on the actual payments platform. This makes it hard to judge daily usability and support responsiveness.
- Pricing details, transaction fees, and lead times are not posted publicly. You must contact the company for cost estimates.
- The offering prioritizes regulated hemp, CBD, and cannabis merchants. Mainstream retail merchants may find the focus too narrow.
When It May Not Fit
If you need an off the shelf payment gateway or a packaged merchant software product, StokePay may not match your needs. The service leans toward consultative merchant services rather than sell a standalone payments app. Also, merchants that require transparent published pricing will need to ask for quotes directly.
Who It’s For
High risk merchants in hemp, CBD, and cannabis who need help with compliance paperwork, underwriting readiness, and cash reduction at point of sale. Dispensary owners, cannabis retailers, and ISOs or agents placing accounts in these verticals will find the consultative approach useful.
Real World Use Case
A regulated cannabis dispensary installs a cashless ATM solution to accept card based payments without large cash drawers. StokePay supports the rollout by preparing underwriting documents, connecting the dispensary to an acquiring path, and advising staff on transaction handling and reconciliation.
Pricing
Not applicable. The listing is informational only and StokePay does not publish standard pricing on its site. Prospective merchants should contact the company for custom pricing, fee schedules, and expected lead times.
Website: https://stokepay.com
QuadraPay
At a Glance
QuadraPay reports it has served over 5,000 merchants across more than 40 countries since 2016. The firm focuses on high risk verticals such as CBD, gaming, travel, healthcare, and eCommerce. QuadraPay positions itself as a connector to globally acquiring banks rather than a direct processor.
Core Features
According to the company, QuadraPay maintains a network of over 50 acquiring partners that it uses to place merchant accounts. The vendor advertises application reviews in 24–72 hours, and it supports card payments, ACH, virtual terminals, retail POS, offshore processing, and crypto where permitted. The platform groups industry-specific solutions to match underwriting profiles across jurisdictions.
Key Differentiator
That partner network is the main differentiator. QuadraPay routes merchants into acquiring relationships tailored to complex underwriting profiles that many direct processors avoid.
Pros
The vendor advertises approval rates up to 98%, which can matter for merchants repeatedly denied by mainstream processors. Long market experience since 2016 and a broad geographic footprint help place accounts across multiple jurisdictions. Acting as a connector lets QuadraPay match merchants to banks whose risk appetite fits the merchant profile.
Cons
-
Customer reviews show frequent communication problems and unresponsiveness, with many merchants reporting slow support and hard-to-reach account teams.
-
Bureaucratic application and billing workflows can lengthen onboarding and frustrate merchants used to transparent processes.
-
QuadraPay does not process transactions directly, which reduces merchant control over settlement details and day to day account management.
When It May Not Fit
If you require a direct processor that controls settlement and chargeback workflows, QuadraPay is not a good fit. If predictable, published service level agreements are critical for daily operations, the connector model can introduce variability. If you need public, fixed pricing and turnkey account control you should look elsewhere.
Who It’s For
You are a high risk or high growth merchant selling regulated goods or services and need access to acquirers across borders. QuadraPay suits businesses willing to trade direct processing control for broader acquirer access. You should have compliance resources and the ability to manage partner-driven accounts.
Real World Use Case
A European CBD brand used QuadraPay to secure multiple acquiring relationships for EU and US sales. That placement reduced card declines and opened ACH and multi currency payment options. The acquiring partners handled underwriting while the merchant focused on market expansion.
Pricing
QuadraPay does not publish public pricing. Pricing is handled case by case and tied to the acquiring relationship and merchant risk profile. Merchants receive fee details during application and onboarding.
Website: https://quadrapay.com
L3 Payments
At a Glance
Places merchants with FDIC insured banks and supports real time FedNow and RTP payments. The firm acts as an agent office that manages merchant accounts and advocates with sponsor banks through the account lifecycle. Public reviews describe strong banking relationships but raise repeated concerns about sales tactics and support quality.
Core Features
L3 Payments places merchant accounts and manages them over time while providing risk tools and chargeback prevention services. The offering includes real time bank transfers via FedNow and RTP plus business intelligence through MidBI for payment performance and fraud signals. The team also coordinates compliance and ongoing account advocacy with partner banks.
Key Differentiator
The firm focuses on matching merchants to suitable FDIC insured banks and then managing the merchant account lifecycle. That placement plus active bank relationships aims to reduce application friction for regulated or high risk verticals. The vendor positions ongoing advocacy and compliance support as the central service differentiator.
Pros
Strong bank relationships can translate into higher approval rates for merchants that require specialized sponsor banks. Ongoing account advocacy and compliance coordination help merchants navigate underwriting questions and processor reviews. The product mix covers card acceptance, ACH, and instant bank rails, while analytics give transaction level visibility for fraud and performance.
Cons
- Aggressive and persistent sales calls reported by multiple reviewers. These calls can feel intrusive for merchants evaluating options.
- Unresponsive or rude customer support interactions appear in user feedback. Slow or poor service may delay issue resolution.
- Credibility concerns and suspicious marketing practices have been raised by reviewers. Those perceptions can affect trust during onboarding.
- Reputation is marred by multiple negative service experiences in public comments. That record may complicate relationships with sensitive merchants.
When It May Not Fit
Not suitable for merchants that want direct banking services or a bank charter. L3 Payments only operates as an agent office and cannot provide bank licensing. Merchants that require white glove support or a spotless public reputation should weigh reported service complaints before committing.
Who It’s For
Merchants that need help placing a merchant account with an acquiring bank and want active advocacy after approval. Businesses that plan to use instant bank transfers and need payment analytics will find the feature set relevant. This fits merchants willing to accept tradeoffs on support and marketing behavior for stronger bank placement options.
Real World Use Case
A retail chain uses L3 Payments to place merchant accounts across multiple states and to clear large ACH settlements. The chain receives faster settlement options via FedNow for same day funding and uses MidBI to flag fraud indicators. L3 Payments manages bank relationships and handles disputes on the chain’s behalf.
Pricing
Not applicable. The company lists its services as informational and placement oriented rather than a fixed price product. Merchants should request a custom placement quote during outreach.
Website: https://l3payments.com
Durango Merchant Services
At a Glance
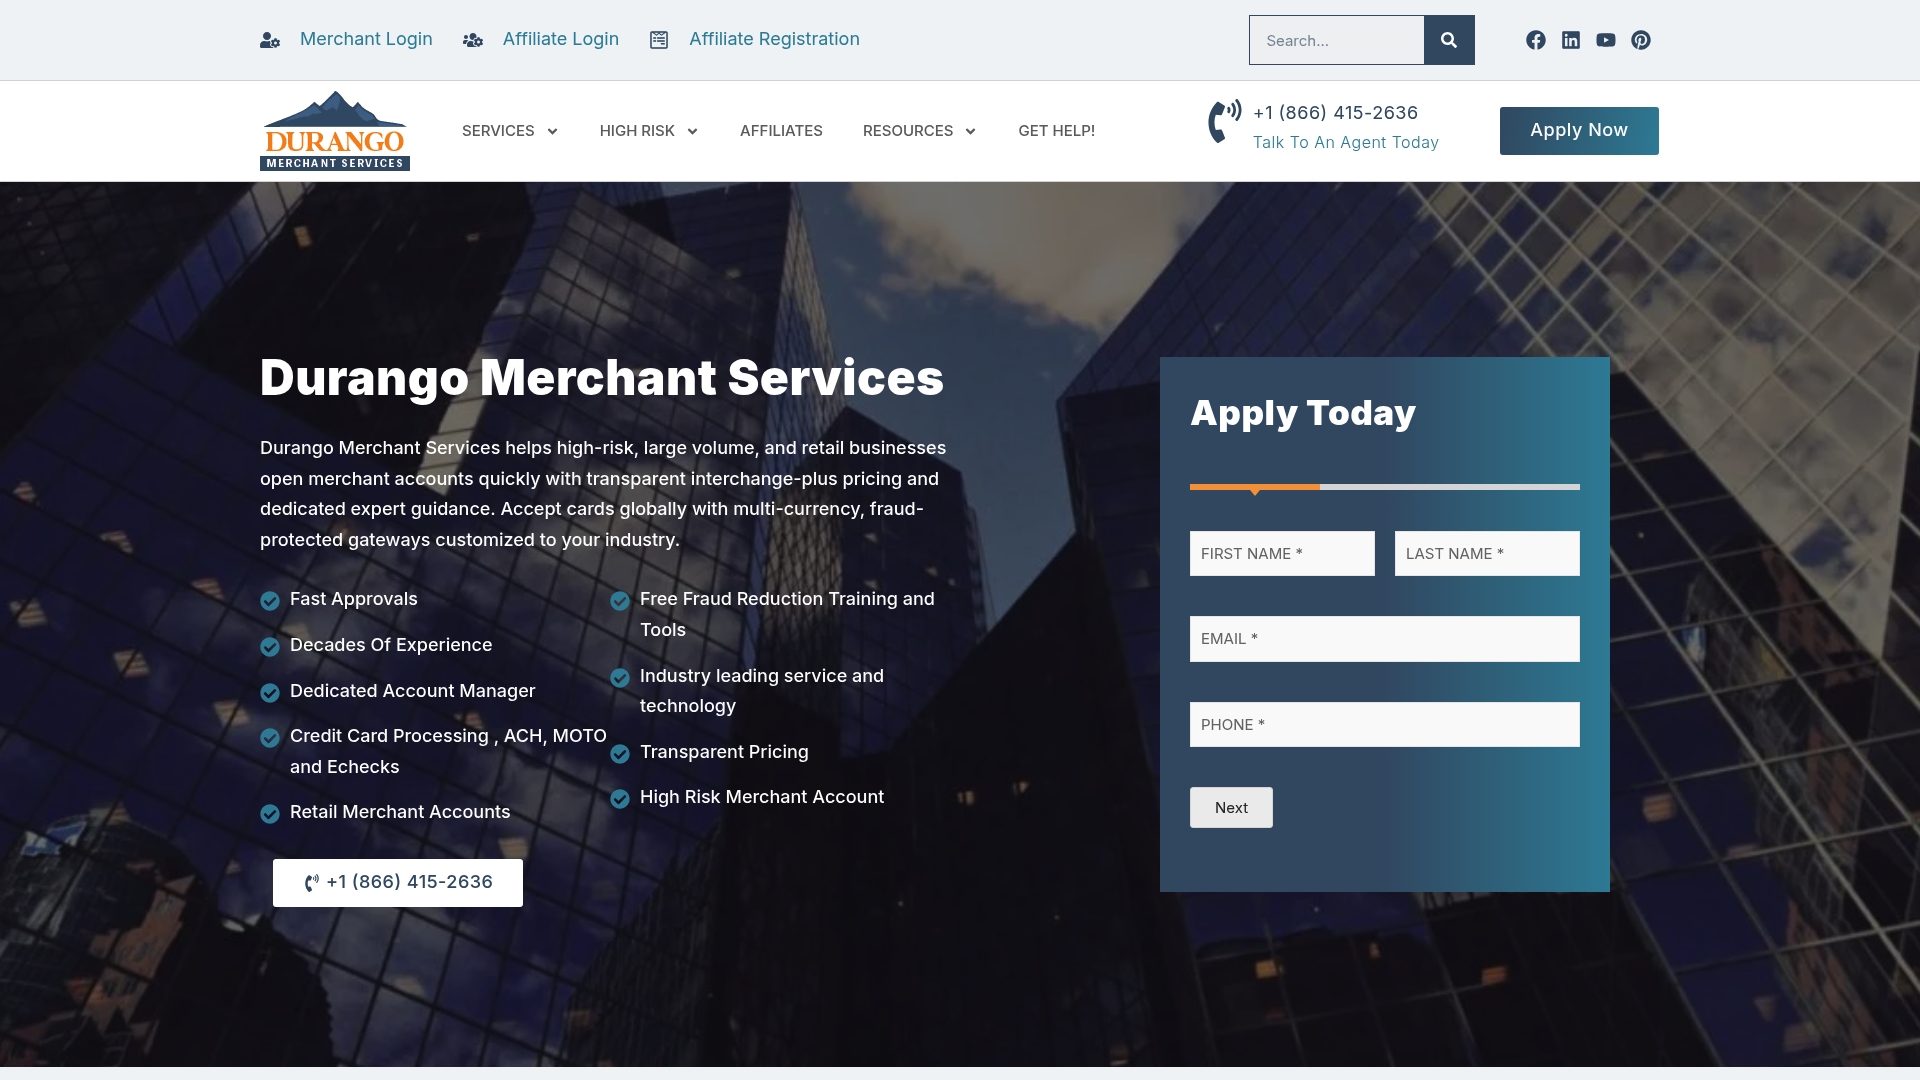
Durango Merchant Services reports over 20 years of experience supporting high risk and large volume merchants. The vendor advertises transparent interchange plus pricing and dedicated account managers for personalized onboarding. It emphasizes multi currency acceptance, fraud protected gateways, ACH, eChecks, and MOTO services.
Core Features
The vendor advertises broad integration with over 150 shopping cart platforms and multi currency gateway support. Service includes fast approvals for merchant accounts, dedicated account manager support, and interchange plus pricing models. They also provide ACH, eChecks, digital wallet acceptance, custom fraud protection, account recovery, and help raise processing limits.
Key Differentiator
Durango’s primary edge is specialized expertise in high risk merchant account setup and ongoing support. That expertise pairs with personalized account management that adapts underwriting and gateway configurations to vertical specific needs. This focus fits merchants who need hands on help increasing processing limits and maintaining international acceptance.
Pros
Strong strengths include hands on support for high risk industries and tailored onboarding via a dedicated account manager. Clients report useful assistance with account recovery after closures and practical help raising processing limits when volume grows. Transparent interchange plus pricing makes cost composition visible for large volume merchants. Gateway flexibility and multi currency capabilities support expansion into new markets.
Cons
- Polarized user reviews. Some customers praise the company for handling complex setups, while others report perceived discrimination and unresponsive support.
- Reported discrepancies between advertised services and actual experience. Several merchants describe delays or poor communication after onboarding.
- Support responsiveness varies by region and by assigned account manager, which can frustrate teams during disputes or rapid growth.
- Limited appeal for very small startups and low volume merchants who need packaged, turn key plans.
When It May Not Fit
Not ideal for very small startups or single person shops that need fast, simple onboarding and fixed pricing. Complex approval steps can delay time to market for merchants without established transaction history. Variable service quality across regions and account managers may not match teams that require predictable, always on responsiveness.
Who It’s For
Medium to large high risk retail, eCommerce, and international merchants with significant processing volumes will get the most value. Brands that need custom gateway work, multi currency settlement, or help recovering merchant accounts will benefit. Merchants with recurring chargeback issues or complex underwriting needs will find tailored support useful.
Real World Use Case
A supplement manufacturer with a history of chargebacks used Durango for a tailored high risk merchant account. The company helped expand multi currency acceptance and raised processing limits to support new international channels. That change let the merchant keep processing while improving dispute workflows and underwriting documentation.
Pricing
Pricing is listed as not applicable and appears informational only. Durango advertises transparent interchange plus pricing rather than fixed flat rate tiers. You must contact sales for a customized quote based on volume, vertical, and risk profile.
Website: https://durangomerchantservices.com
Comparison of alternatives
When selecting a payment processor for high-risk industries, balancing approval timelines, compliance features, and operational support becomes. Let’s evaluate the major players in this sector to highlight their unique strengths and narrow down the choice for specific needs.
Onboarding speed and compliance support
DavinciPay advertises approvals within 24 hours, which is crucial for merchants transitioning services without disrupting their operations. In contrast, QuadraPay’s onboarding process, ranging from 24–72 hours, offers a broader range but less urgency. StokePay provides detailed compliance support but does not emphasize expeditious onboarding, targeting niche cannabis-related industries instead.
Global coverage and banking partnerships
Adaptiv Payments supports global currency processing and provides access to an extensive network of acquiring banks. This makes it particularly suited for merchants operating internationally, requiring reliable banking relationships across borders. Conversely, Durango Merchant Services offers multi-currency capabilities but focuses on customized services for specific industries rather than broad global adaptability.
Best fit
- Merchants needing fast underwriting and compliance monitoring should consider DavinciPay for its rapid onboarding process and built-in payment tracking tools.
- Businesses requiring global banking connections and versatile currency processing should opt for Adaptiv Payments, which emphasizes international market access.
- Dispensaries looking for payment solutions that minimize cash handling can benefit from StokePay’s dedicated cashless ATM services and compliance consultation.
Our pick
DavinciPay excels as the top recommendation for merchants prioritizing speed and support integration in compliance-dependent verticals. Its rapid onboarding and active compliance monitoring reduce operational downtime, making it a preferred choice in high-pressure industries. However, businesses aiming for extensive global reach should also examine Adaptiv Payments for their specific needs.
To determine which provider offers the fastest and most specialized process for high-risk merchant accounts, this comparison highlights key features and considerations of viable alternatives.
| Provider | Core Feature | Key Differentiator | Best For | Pricing | Notable Limitation |
|---|---|---|---|---|---|
| Davincipay | PCI Level 1 certification, real-time dashboard | Fast onboarding and specialized support for high-risk verticals | CBD, nutraceutical, telehealth, gaming, adult | Price not published | Limited public detail on pricing indicators |
| Adaptiv Payments | Real-time multi-currency fraud monitoring | Specialized high-risk underwriting with global banking connections | CBD, gaming, nutraceutical, travel | Price not published | Absence of reported user feedback on specifics |
| StokePay | Cashless ATM solutions for dispensaries | Focused consultative onboarding for regulated industries | Hemp, CBD, cannabis | Price not published | Lack of public feedback on platform usability |
| QuadraPay | Network with over 50 acquiring partners | Acquirer matching for complex underwriting profiles | High-risk goods or services internationally | Price not published | Communication problems noted in reviews |
| L3 Payments | Instant transfers via FedNow and RTP | Account placement with FDIC-insured banks and active advocacy | High-risk online and retail | Price not published | Persistent sales and support issues reported |
| Durango Merchant Services | Transparent interchange plus pricing | Expertise in high-risk accounts with dedicated account management | Large volume international eCommerce | Price not published | Polarized reviews on service responsiveness |
What Challenges Do Merchants Face When Searching for PlushPay.com Alternatives?
Many high-risk merchants struggle with frequent declines, slow onboarding, and limited ongoing support when traditional processors do not accept their business. Finding payment solutions that offer fast approvals, chargeback mitigation, and underwriting support remains the top priority. Businesses in CBD, nutraceuticals, telehealth, and subscription services need reliable access to compliant merchant accounts and payment gateways to maintain steady cash flow.
Davincipay meets these challenges head-on by providing rapid onboarding within 24 hours combined with real-time dispute monitoring and fraud prevention tools. Merchants receive ongoing underwriting assistance designed to reduce the risk of account holds and freezes. Learn how Davincipay offers the support high-risk ecommerce brands require and benefit from a tailored payment infrastructure.
Looking for dependable processing beyond PlushPay.com alternatives? Visit Davincipay now to request a customized quote and secure payment acceptance designed for your industry and transaction needs.
FAQ
What approval speed does DavinciPay offer for high-risk merchants?
DavinciPay provides a fast approval process that can take place within 24 hours. This quick onboarding is a critical feature, especially for merchants who require immediate access to payment processing services. To ensure you’re set up quickly, reach out to DavinciPay directly for assistance.
How does DavinciPay compare to Adaptiv Payments in terms of customer support?
Adaptiv Payments offers helpful customer support and industry expertise, which can be critical for understanding regional compliance requirements. For high-risk merchants who need quick and proactive responses, DavinciPay focuses on personalized ongoing support that reduces the risk of account freezes. This makes it a strong contender for businesses requiring continuous assistance.
Can I track disputes and payouts with DavinciPay?
Yes, DavinciPay features a real-time dashboard that tracks payments, disputes, and payouts. This allows merchants to react quickly to chargebacks and manage financial flows efficiently. Utilize this dashboard to maintain visibility over your transactions and operations.
What unique features does DavinciPay offer for high-risk sectors?
DavinciPay specializes in servicing industries that traditional processors often decline, such as CBD, telehealth, and adult services. Their emphasis on personalized support helps reduce the common friction these merchants face. Engage with DavinciPay to benefit from custom solutions tailored to your high-risk business needs.
What advantages do other platforms have over DavinciPay?
Many other platforms, like QuadraPay, have a wide network of acquiring partners, which provides them with high approval rates for underwritten accounts. This can be beneficial for merchants who face repeated denials from mainstream processors. However, DavinciPay’s focus on specialized support for high-risk businesses may offer more value for your specific needs.



